
CBN Sets Tough Rules for Stablecoins and Crypto Firms
By Patience Ikpeme
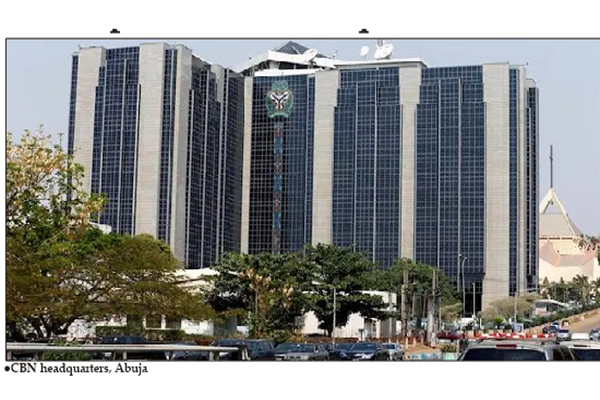
The Central Bank of Nigeria (CBN) has set out a detailed rulebook for digital currencies used to pay, send and settle money. The rules cover stablecoins, which are digital tokens built to hold a steady value, and the companies that issue, sell, store and move them.
The rulebook is titled Regulations for the Operations of Non-Security Virtual Assets in Nigeria. It says the aim is “to support responsible innovation while safeguarding the integrity, stability, and efficiency of the Nigerian financial system.”
The apex Bank also names the risks that worry it. These include threats to financial stability and monetary policy, harm to consumers, dirty money, weak technology and the control of foreign exchange.
The rules cover three kinds of token. Class 1 stablecoins are tied to the Naira. Class 2 stablecoins are tied to a foreign currency such as the US dollar. Deposit Money Tokens are digital versions of money already held in a bank account. The CBN can also add other tokens to the list.
Tokens that work like shares or investments stay with the Securities and Exchange Commission (SEC). The CBN keeps control of anything to do with payments, settlement and foreign exchange. The rules say the CBN will decide a product’s category by what it actually does. In its words, “the categorisation, characterisation or description of a token, product, arrangement or service by any person is not determinative of its regulatory treatment.”
The rulebook is direct on licensing. “No person shall conduct, or hold itself out as authorised to conduct, a Regulated Activity without the licence, authorisation or approval required by these Regulations,” it says.
Foreign firms are not exempt. The rules state that “an overseas location does not remove an activity directed at Nigerian persons from the scope of these Guidelines.” Any company that issues a stablecoin for Nigerians must be set up in Nigeria, have a staffed office here, and keep a compliance officer who lives in the country. A foreign licence will not do instead. The rules say bluntly that “there is no offshore issuer exemption from incorporation, licensing or capital.”
Companies must show they have serious money behind them. A Class 1 issuer needs at least ₦10 billion in paid-up capital. A Class 2 issuer needs at least ₦15 billion. Firms that offer other services, such as wallets, exchange, payments and transfers, need at least ₦1 billion. This is on top of any capital the SEC or another regulator already requires.
The capital must be cash held at the CBN, or Federal Government securities held under a CBN lien. Crypto assets and promises of future money do not count. Issuers must also keep enough of their own liquid funds to cover six months of running costs, or the cost of closing down in an orderly way, whichever is higher.
The application fee for an issuer licence is ₦10 million, and the yearly renewal fee is ₦5 million.
Some tokens are banned outright in Nigeria. These include stablecoins that hold their value through computer formulas instead of real backing, and tokens backed mainly by other crypto assets. Tokens from sanctioned people or places are banned too. So are tokens that do not give holders a firm right to cash out at full value.
The strongest protections are for people who hold the tokens. Every issuer must keep enough reserves to back every coin in circulation, one for one, plus an extra 2 per cent cushion. It cannot create new coins until the matching money has arrived. The rulebook says plainly that “no new tokens shall be minted unless equivalent Eligible Reserve Assets have been received.”
At least 40 per cent of the reserve must be cash or assets that can quickly be turned into cash. Naira stablecoin issuers must also keep 20 per cent of their reserve as a deposit at the CBN that earns no interest. The reserve may be held in Treasury Bills, Federal Government bonds, bank deposits and a few similar safe assets. No single bank may hold more than 30 per cent of it.
The reserve must be kept apart from the company’s own money and held on trust for coin holders. If the company fails, holders come first. The CBN will then appoint a special administrator to pay holders back. The rules also say reserves may not be lent out, pledged or invested in risky ways. They state that reserve assets “shall not be used for any purpose other than supporting redemption and permitted liquidity management.”
Holders have, in the rulebook’s words, “an absolute, legally enforceable right to redeem their stablecoin tokens at par value at any time.” Issuers must pay out by the end of the next working day. They may not charge a fee for a normal withdrawal. Payouts can be paused only in four cases. These are a court order, a CBN directive, a serious technical fault, or a CBN order for a coin that has become too big to fail. An issuer that pauses must tell the CBN within one hour. It may not keep the pause going beyond 48 hours without the CBN’s written approval.
Stablecoin issuers may not pay interest or any other reward for holding their coins. The rules say an issuer “shall not pay, offer, arrange or facilitate interest, yield, dividends, returns or other financial benefits to holders.” Breaking this rule attracts a fine of twice the amount paid out.
The rules also tell the public what stablecoins are not. “Stablecoins shall not be represented as bank deposits or as covered by NDIC deposit insurance,” they say. A CBN licence is no guarantee either. The rules state that a licence or approval “shall not be represented as an endorsement or guarantee by the Bank.”
Using crypto to send money across the border will be treated like any other foreign exchange deal. Firms must ask for the same papers, such as Form M for imports and Form NXP for exports. Export earnings kept in a crypto wallet will not count as brought home. The rules say that “holding the export proceeds on-chain in a wallet, in Nigeria or elsewhere, shall not constitute repatriation.” The money must be turned into Naira or paid into an export proceeds account with an authorised dealer.
The CBN also warns against using crypto to dodge the foreign exchange rules. “The use of a Regulated Token or P2P Service shall not alter the regulatory treatment of the underlying economic transaction,” the rules say. A person also cannot use crypto to “undertake through a virtual asset a transaction that would not otherwise be permissible” through normal banking channels. The CBN can cap transfers, close certain routes or stop conversions between Naira and foreign-currency coins if the foreign exchange market comes under pressure.
Foreign-currency stablecoins cannot be used to pay for goods or debts priced in Naira, except where the law allows it.
Platforms that match buyers and sellers of digital coins, known as P2P services, can only run with a licence and the CBN’s specific approval. A platform may not release coins until it confirms that the name and Bank Verification Number on the Naira bank account “match the verified customer on whose behalf the provider acts.” This is meant to stop the use of borrowed or fake accounts. Platforms must also spot traders who are really running a business, and check them more closely.
Every licensed firm must know its customers. Identity checks are needed for transactions of 1,000 US dollars or euros and above, or at any amount if something looks suspicious. Details of the sender and receiver must travel with transfers at that level. A firm that cannot send the details must not make the transfer. Suspicious activity must be reported to the Nigerian Financial Intelligence Unit within 24 hours. Records must be kept for five years.
Issuers must be able to freeze, block and cancel tokens when a court or the authorities order it. The rules also close a possible loophole. “Describing an arrangement as decentralised, or the use of smart contracts, shall not of itself remove the arrangement from the scope of these Regulations,” they say.
Issuers must have their smart contracts checked by two independent security firms before launch or a major upgrade. They must also run a yearly hacking test, and their main platform may be down for no more than four hours in any three months. They must check their reserves every working day. They must publish a monthly reserve report prepared by an approved independent auditor within 15 working days of month-end.
Penalties are steep. Running a business without a licence draws a fine of at least ₦100 million, plus at least ₦1 million for each further day. Using reserves for lending or other banned purposes carries a fine of between ₦250 million and ₦500 million for each breach. Lying to the CBN or the public about reserves draws at least ₦500 million, and the case can go to prosecutors. Failing to carry out checks against crime attracts at least ₦50 million per breach. The CBN can also suspend or cancel licences and publish the names of unlicensed operators. A firm facing a fine has 15 working days to respond before it is final.
Banks have their own track. A bank may issue Deposit Money Tokens, which are digital claims on money already in a customer’s account, once the CBN approves. These tokens can be cashed in at full value. Transfers between banks must be settled through the CBN’s own settlement system.
Companies already operating must register with the CBN within 30 days of the rules coming into force. They must start reporting to the CBN within 60 days and apply for a licence within 180 days. A firm that misses that deadline must stop operating until it is licensed.
For ordinary users, the rules mean that only licensed firms may sell or hold stablecoins for them. A holder who owns a licensed stablecoin can claim full value back within a day. Customers should expect stricter identity checks, and some trades that look easy today may become harder. They should also keep in mind that a stablecoin is not a bank deposit and has no NDIC cover.